

Since July 2026, Reclaim Finance has questioned more than sixty international banks on how their coal policies treat captive coal – coal plants built to power a single industrial site (aluminium, nickel, steel) rather than the public grid.(1) The main finding from this update to the Coal Policy Tracker: most policies do exclude direct financing of a new captive coal plant, but that protection collapses as soon as financing covers the broader industrial project, or as soon as financing becomes indirect as general support to the client company planning captive coal. Reclaim Finance calls on banks to close these gaps at every level of their policies.
Captive coal is a structural blind spot in the global coal phase-out. While a record number of banks have committed to exit coal, captive plants have remained largely untouched by these commitments – and are growing precisely because they fall outside the scope of most existing sectoral policies.
In Indonesia, Earthwise Institute's database identifies at least 23.9 GW of operating captive coal capacity – more than 40% of the country's total coal-fired power capacity – and a further 19.2 GW in the pipeline, bringing the expected total to over 43 GW.(2) This capacity serves private industrial interests (nickel, aluminium) rather than public electricity access: on many islands where communities have no reliable grid connection, captive plants are built exclusively for industrial parks, leaving those communities behind. The climate and health consequences are severe and worsening.(3)
To pin down this blind spot, Reclaim Finance tested banks' coal policies against three levels:
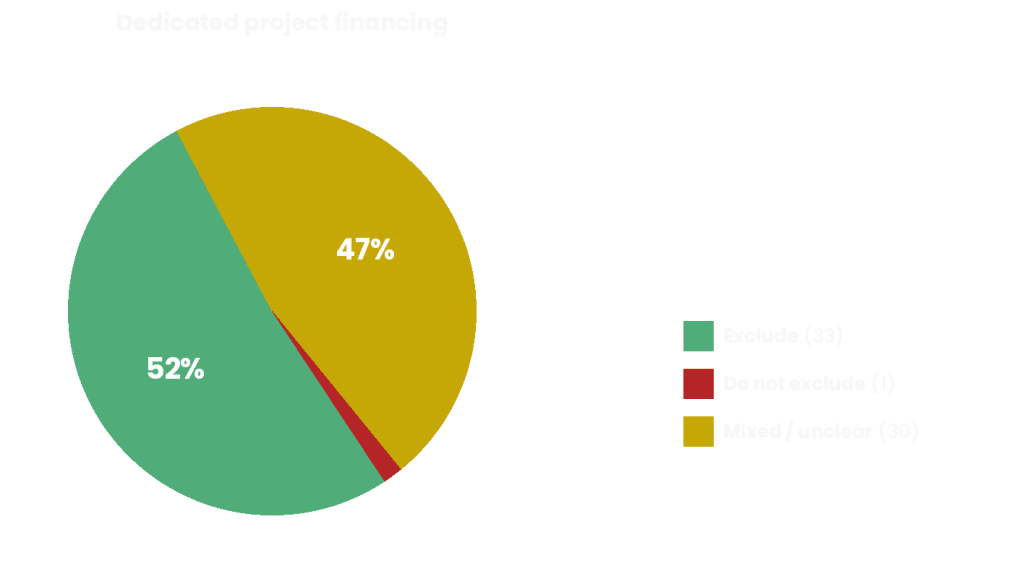
- Dedicated project financing: does the exclusion apply when financing specifically targets a captive coal plant?
- General financing of an industrial project that includes a captive plant: does the exclusion still apply when financing is not earmarked for the plant itself but for the industrial project as a whole?
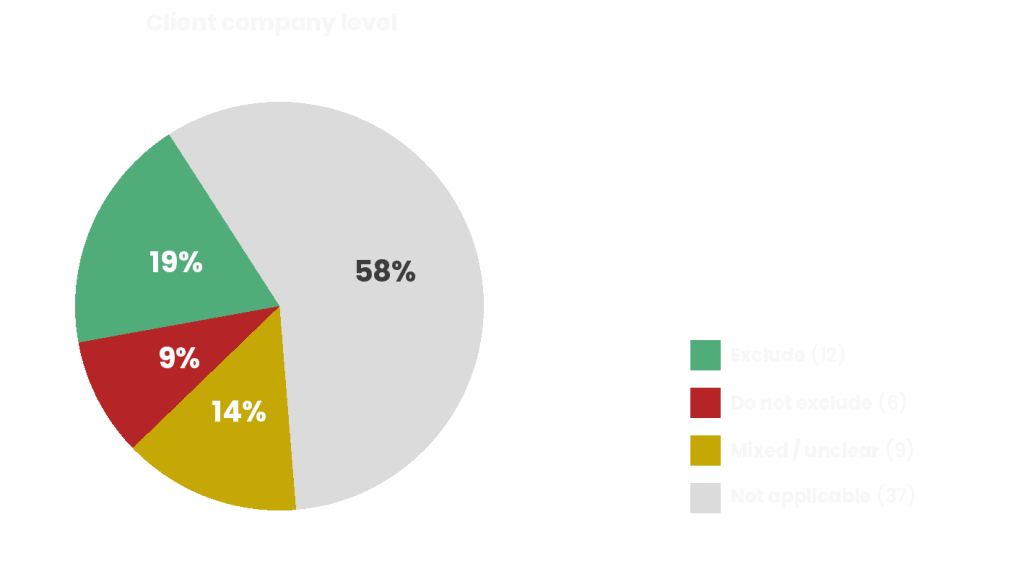
- The client company level: does the policy exclude companies developing a captive plant for their own industrial needs, independently of any project financing?
Dedicated project financing: the strongest line of defence
On this question, most banks answer clearly with an exclusion. BNP Paribas, Crédit Agricole and Société Générale all confirm that their exclusion of new coal plants applies regardless of where the electricity ends up. HSBC is explicit in its policy stating that it 'will not finance the creation of new captive thermal coal facilities', defining captive plants as 'thermal coal-fired power plants dedicated to a specific project or industrial facility, such as an aluminium smelter, a steel mill or cement plant, and the majority of power generation is for the client's own use', and excluding them on the same terms as grid-connected ones.(4)
Once financing turns general, the protection weakens
The strength of these policies erodes as soon as financing moves away from the plant itself.
- BNP Paribas says it only deploys its "best efforts" to ring-fence financing within a broader industrial project;
- UniCredit states that this scenario is not explicitly within the scope of its coal policy and is assessed case by case;
- Morgan Stanley confirms outright: The Policy itself does not exclude financing the whole facility.
- Standard Chartered goes further still: its policy carves out an explicit exemption for captive coal use in aluminium, cement or steel, provided the financing dedicated to the plant itself is ring-fenced.
One real transaction shows exactly how this gap plays out in practice. In 2021, BNP Paribas financed the expansion of the PT Halmahera Persada Lygend nickel smelter in Indonesia, despite a policy that restricts direct financing of projects expanding the coal sector, including captive plants. Reclaim Finance's Behind the Smokescreen briefing documents that BNP Paribas defended the deal by arguing its contribution financed only "other components" of the project, not the coal plant itself – an argument the briefing dismisses given that money is fungible and the coal plant is an integral part of the industrial project.

At the company level, the blind spot widens further
It is at the level of the client company that the gap is the widest – or hardest to assess.
- BNP Paribas' sectoral coal policy only encompasses power generating companies, leaving out industrial groups that operate a captive plant for their own production.
- BPCE-Natixis, for its part, simply refers back to its internal definition of "Developer" without ever confirming whether captive plants fall under it – too evasive an answer to count as an exclusion.
- Société Générale acknowledges that when captive electricity is not the subject of a booked transfer price, the very existence of these facilities 'cannot be systematically identified', which is wrong since all companies planning more than 100 MW of coal power expansion, including captive plants, are gathered in the Global Coal Exit List.(5)
- Standard Chartered, finally, carves out an explicit exemption for captive use where there is no economically viable alternative. The result: a company can build a coal plant for its own industrial needs without ever triggering an exclusion at the company level.
Another real transaction shows exactly how this gap plays out in practice. In September 2024, Crédit Agricole CIB led a US$155.6 million syndicated term loan to Titan AL-TEC & Resource, (6) a Singapore-based financing vehicle of China's Tianshan Aluminum Group, structured as general corporate financing but predicted mainly to fund Tianshan's Indonesian expansion – including a new alumina refinery paired with its own 160MW captive coal plant.(7) Reclaim Finance flagged the transaction to Crédit Agricole in October 2025, noting that the loan appeared to comply with the bank's own coal policy only because the plant's 160MW capacity falls under a 300MW threshold applied to coal developers. A general, non-earmarked loan reaching the group building the plant was compounded by a second loophole: a capacity threshold seemingly built for grid-scale coal plants, used here to clear a captive one.
These findings confirm what Reclaim Finance has documented for years in its Coal Policy Tracker: the financial lever works to constrain coal expansion but only where policies are explicit. Captive coal keeps growing precisely because it sits in the blind spots of existing policies. Reclaim Finance calls on banks to explicitly extend their coal exclusions across all three levels tested — dedicated project, general project, client company.


